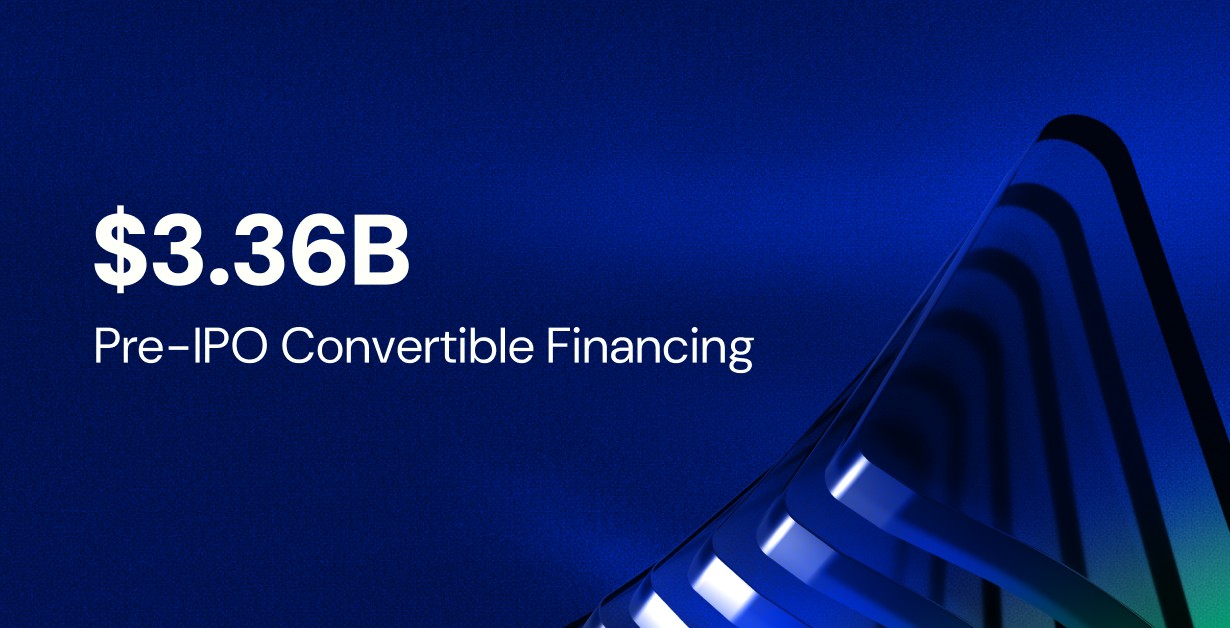
The first tranche lands at closing. The second is committed but unpaid, and it waits on a listing that has not happened yet.
London-based AI cloud provider Nscale said on September 25 that it raised $3.36 billion in convertible notes, with $2.36 billion funded immediately and a further $1 billion pledged by existing shareholder Nvidia, expected to arrive in mid-November. The whole issue converts into common stock automatically once the company completes an initial public offering. Nvidia’s slice converts into non-voting shares.
Convertible debt suits an issuer that expects to be public before its lenders want their money back. It prices inside a straight bond because holders get equity upside later, and here the later is a listing rather than a fixed maturity date. Nscale filed with the U.S. Securities and Exchange Commission on September 18 to list on the New York Stock Exchange under the symbol NSCL.
The buyer group includes funds managed by Apollo, Citadel, Hudson Bay and the Abu Dhabi Investment Council, according to the company. Goldman Sachs acted as placement agent. People familiar with the matter said the notes attracted credit funds that specialize in financing companies with no public equity to trade against.
Market participants expect a valuation near $35 billion when the shares start trading, the Financial Times reported. Nscale’s offering documents disclose more than $103 billion of contracted work on the books.
That ratio is the thing to sit with. A $103 billion backlog supporting a $3.36 billion financing looks almost conservative until you notice that the money does not arrive at once. Infrastructure contracts are drawn down over years, and the counterparties are a small group of model developers whose own capital structures are still under construction.
Nscale’s pitch is physical rather than algorithmic. The company builds its own power supplies, liquid-cooled data centers and large GPU clusters, and it is developing campuses in Norway and West Virginia. Owning generation and cooling matters more than it once did, because utilities in several American regions now quote multi-year waits to interconnect new load. Developers have begun treating on-site power as a scheduling instrument rather than an emergency fallback.
The company’s lineage is short. Nscale was spun out of Arkon Energy, an Australian crypto mining operator, two years ago. Mining businesses had already assembled the three inputs AI clouds need most: cheap electricity contracts, industrial shells wired for heavy electrical service, and crews experienced in running thousands of power-hungry machines at remote sites. Several of those operators have since recast themselves as AI infrastructure companies.
Nvidia’s $1 billion is the second signal in the transaction. The chipmaker has spent two years placing money into the firms that buy its accelerators, a pattern that has drawn questions from investors who wonder whether the same dollars are circling. Making the position non-voting keeps Nvidia’s role financial rather than operational, and it keeps the company’s own governance clean of a supplier that is also its largest vendor.
Analysts said the convertible structure has become routine for late-stage compute companies because it postpones the moment of repricing. A private round sets a price only insiders can test. A convertible note fixes a coupon and a promise about the future, and the future does the appraisal work.
The notes carry an implicit deadline the company did not choose. Because conversion is triggered by a listing, a postponed or abandoned IPO would leave Nscale servicing convertible obligations without the equity event meant to retire them. That is the standard trade in this corner of the market, and it holds while public investors keep paying up for compute.
The sector has repriced twice in eighteen months. Investors have rewarded operators with signed power contracts and punished those with announced intentions, and the spread between the two groups has widened as interconnection queues have lengthened. Contract language, not capacity targets, has become the thing equity buyers read first.
Competition is crowding in from both directions. Hyperscalers are signing their own multi-gigawatt leases, and a crop of neoclouds has raised billions on the premise that specialized operators can build faster than the incumbents. The differentiator has shifted from GPU supply to electricity supply, where contracts are local, slow and politically complex.
Norway offers an obvious advantage and an obvious risk. Hydroelectric power is cheap and abundant, but European data center policy has turned toward restrictions on large new loads, and several countries have begun scrutinizing whether AI campuses should receive priority grid access. West Virginia presents the mirror image: abundant fossil generation, permissive local government, and a shorter path through permitting.
What remains unresolved is the shape of demand on the other side of the backlog. Nscale’s customers are training and serving models at scales that assume continued capital availability for both parties. If appetite for compute keeps compounding, the contracts convert into revenue. If it flattens, the same documents become obligations that everyone would prefer to revisit.