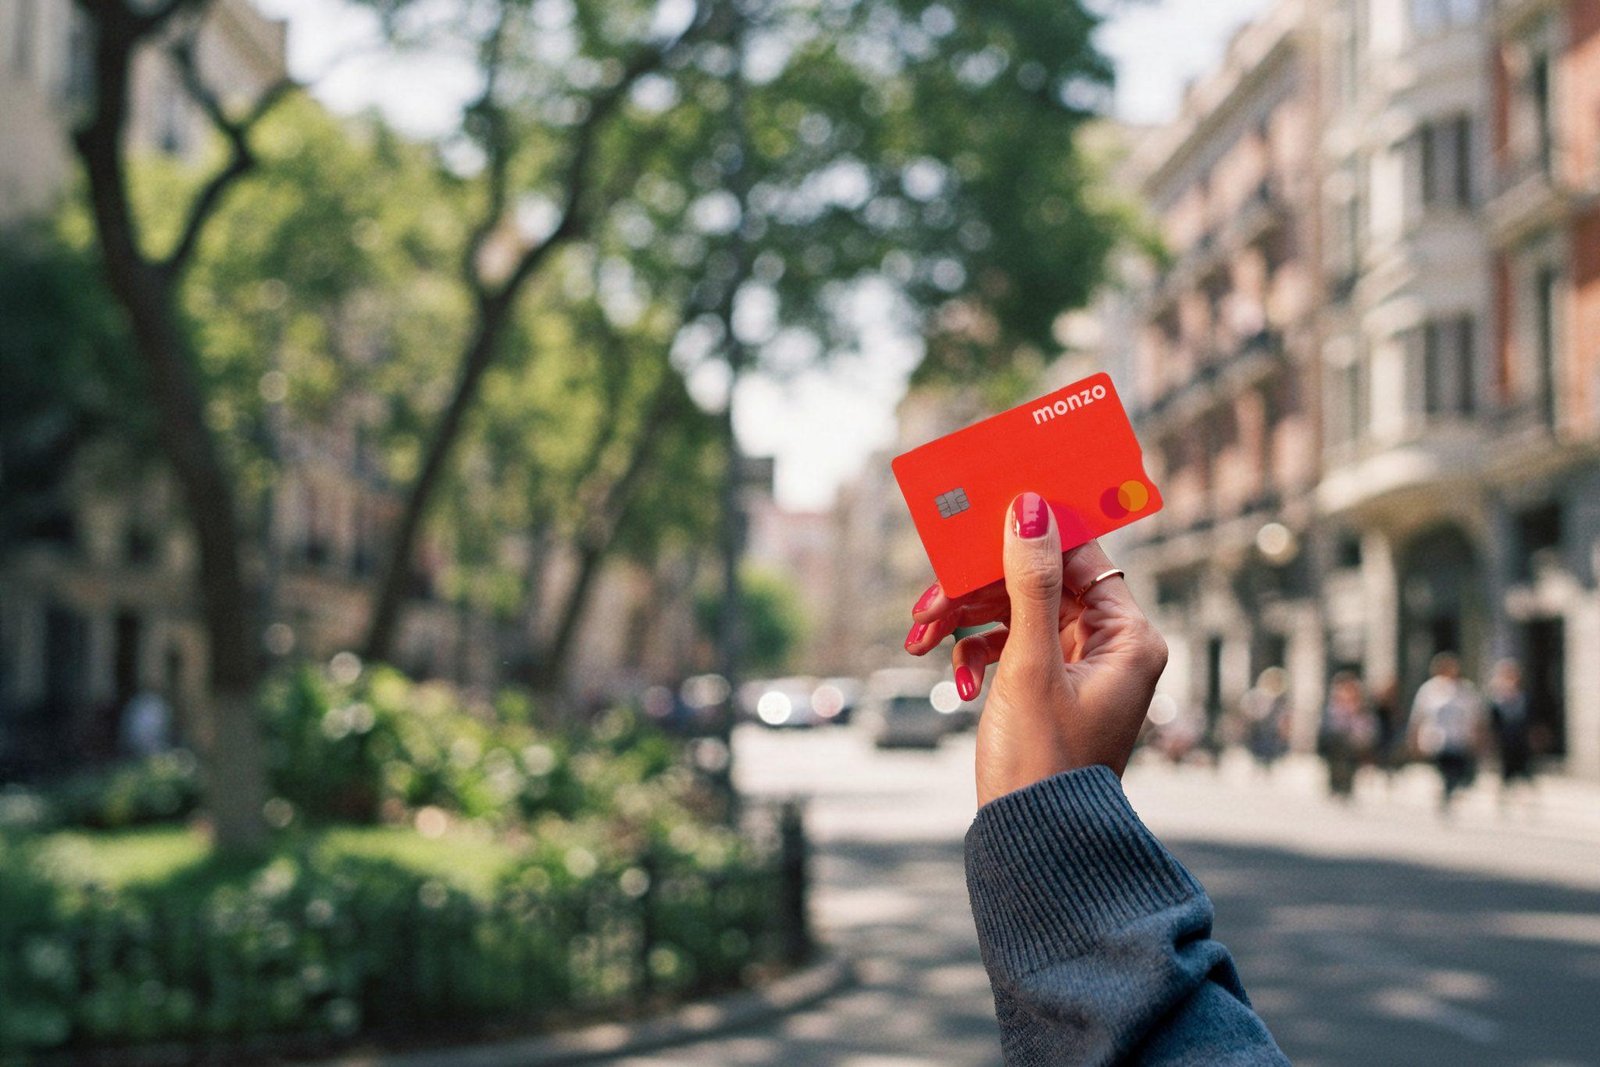
The hot-coral debit card in more than 15 million British wallets was supposed to be the calling card of a future London stock-market debut. Instead, the bank behind the card, Monzo, is now in early talks to sell itself to a rival from Sao Paulo.
Nu Holdings, the New York-listed parent of Brazilian digital bank Nubank, has begun preliminary talks to acquire Monzo in a deal that could value the British fintech at between £8 billion and £10 billion, roughly $10.6 billion to $13.25 billion, Sky News reported Saturday. Reuters and the Financial Times confirmed the discussions, which people familiar with the matter said are at an early stage. The fintech news outlet Sifted described them the same way.
Any takeover would combine cash and shares, according to people briefed on the talks, and would hand Nubank, which already claims about 140 million customers across the Americas, a ready-made foothold in British and European retail banking.
A sale is not the only path under discussion. Monzo is weighing an alternative: a new funding round that would value it above £8 billion, with the proceeds earmarked for an expansion into mainland Europe, the Sky report said.
The gap between the two numbers shows how far Monzo has come. The bank was last valued at £4.5 billion in an October 2024 employee share sale to investors including Singapore’s sovereign wealth fund GIC and StepStone Group. A deal at £10 billion would more than double that mark.
Nubank is a different scale of animal. Founded by Colombian-born entrepreneur David Velez and listed on the New York Stock Exchange in 2021, it carries a valuation of about $65 billion and dominates digital banking in Brazil, Mexico and Colombia. Its interest in Monzo is part of a push beyond Latin America.
For London, the talks are another blow. The London Stock Exchange has long courted Monzo as a potential listing candidate, and the company has repeatedly been mentioned as one of the few British fintechs large enough to anchor a meaningful IPO. A sale to a foreign buyer would remove it from that list.
Monzo has been here before, in a smaller way. The company has previously discussed selling a stake of about 15% to private equity investors, part of a series of secondary deals that have let early employees and backers cash out without an IPO. The Nubank approach is different in kind: a change of ownership, not a share of it.
Monzo’s financials have improved sharply in recent years. Revenue climbed from about £67 million in 2020 to more than £1.2 billion, and the bank reached profitability while growing from a challenger into the country’s largest app-based current-account provider. Its customers span personal banking, business accounts and a fast-growing product for teenagers.
The talks arrive during a leadership change. TS Anil, who has run Monzo since 2020 and oversaw its growth from about four million customers to more than 13 million, announced in October 2025 that he would step down as chief executive. Diana Layfield is expected to take over.
Monzo was founded in 2015 as Mondo by Tom Blomfield and a group of colleagues who had worked together at Starling Bank, and rebranded the following year after a trademark dispute. It won a full UK banking license in 2017 and grew into Britain’s largest app-based current-account provider, a position built on a coral card and an early reputation for treating customers well.
Monzo has been a London story since the beginning. In 2016, then called Mondo, it raised £1 million in 96 seconds on the crowdfunding platform Crowdcube, a record that made it a symbol of Britain’s fintech ambitions. Losing a company like that to a foreign buyer would sting beyond the balance sheet, at a moment when the City is already fighting to keep its technology listings.
Nubank’s interest is not sentimental. The bank, which Velez built into Latin America’s most valuable financial company by signing up customers other banks ignored, has said it wants to repeat that playbook in new markets. A British current-account base with Monzo’s growth rate would give it a licensed entry point into Europe at a time when cross-border digital banking is still rare.
The approach fits a pattern that has run through fintech for two years: richly valued incumbents from one region buying their way into another. A Nubank-Monzo combination would marry a Latin American giant with a British challenger at a moment when European digital banking is consolidating, and when higher interest rates have made deposit-rich banks more valuable.
The talks are early, and either side could walk away. What is already clear is that the bank once seen as a poster child for British fintech is now the subject of a conversation in which London may not get the final word.