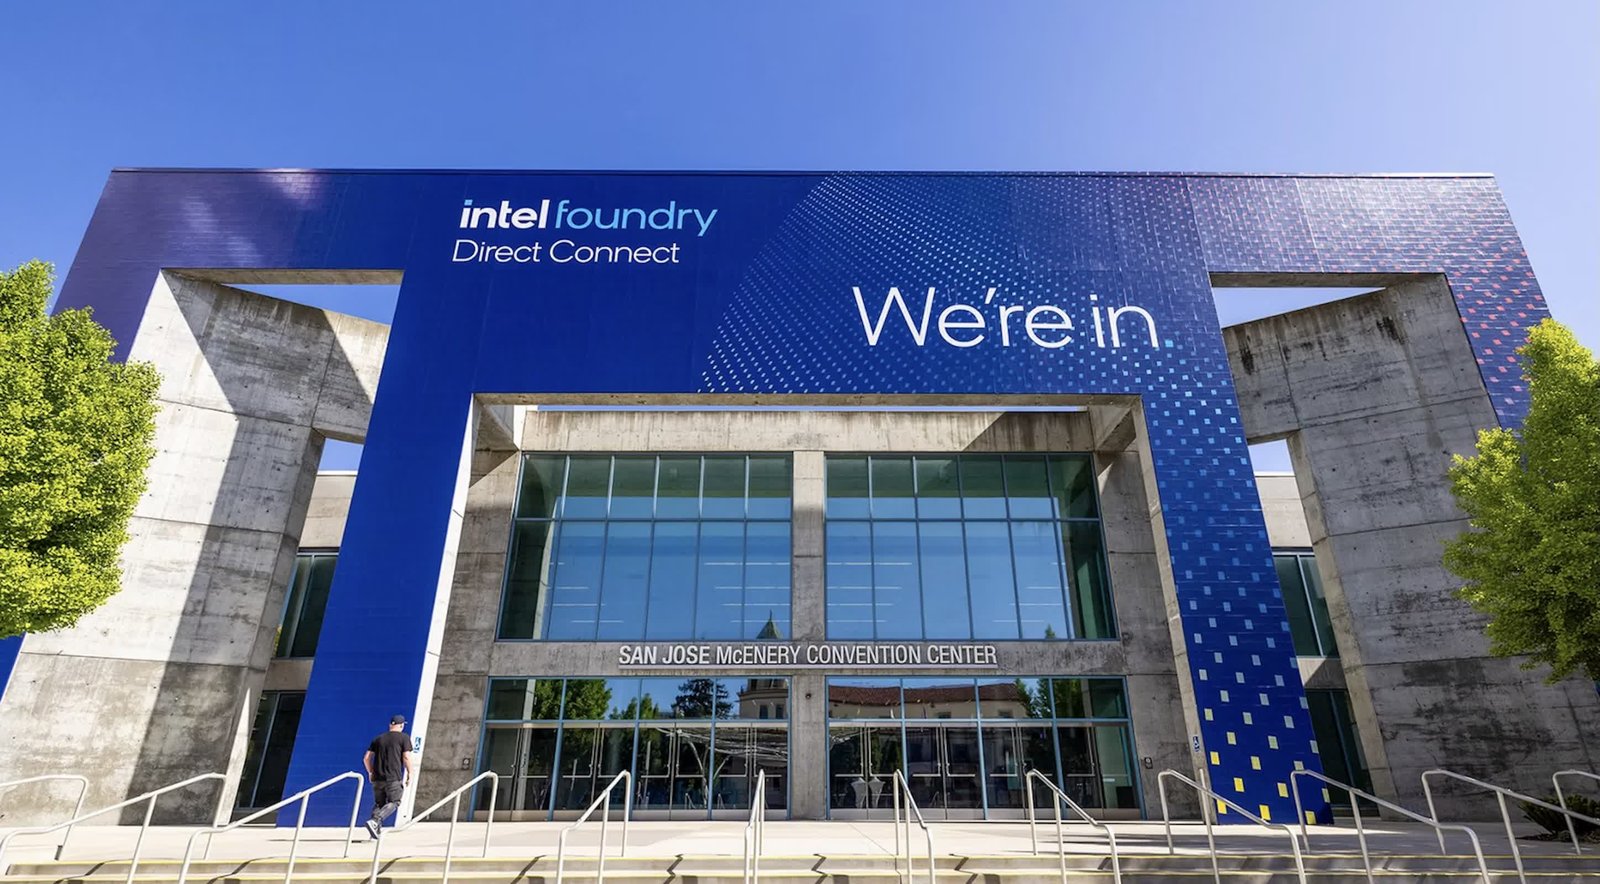
Intel needs one customer willing to commit first. According to Piper Sandler, nearly every other large U.S. buyer is already asking questions.
A research note from the investment bank says Amazon, Apple, AMD, Google, Tesla, Microsoft, Nvidia and Qualcomm are all evaluating Intel’s 14A manufacturing process. Two forces drive the interest, the note says: the process’s technical specifications have come in better than expected, and TSMC’s capacity is booked out through 2028, leaving customers who want a second source for manufacturing and advanced packaging with few alternatives.
The list of names carries an awkward symmetry. Several of the companies evaluating Intel’s factory are the same ones that compete with Intel in the markets for processors, accelerators and consumer devices. A foundry business asks its owner to build chips for rivals, and Intel’s pitch now depends on persuading those rivals to trust it with their most valuable designs.
The argument built for them rests on a simple fear. Every large chip designer now depends on a single supplier for leading-edge production, and a single point of failure is an uncomfortable position at this scale. TSMC’s fully committed schedule turns that discomfort into a line item, because a customer that cannot get capacity when it needs it cannot ship a product on time no matter how good the design is.
What Intel lacks is the customer that turns interest into a plan. Piper Sandler’s note warns that the company needs to secure an anchor customer somewhere between late 2026 and early 2027 to support a volume ramp in 2028. An anchor customer is the buyer who commits to volume before a process is proven at scale, and whose order justifies the equipment spending and the yield work that make everything else possible.
Without one, the ramp is a promise with no buyer behind it. Intel raised $2 billion in a stock offering last month, a move the note reads as a signal of confidence that the customer will come. The offering can carry a second meaning as well: money to finish preparing the factories before the orders arrive. Both readings fit the facts, and the difference between them is the anchor customer.
14A is the generation on which Intel has staked its foundry ambitions. If the process wins external customers, the company becomes a genuine alternative in the market for leading-edge manufacturing and a second option for the advanced packaging that increasingly determines what a chip can do. If it does not, the foundry effort remains a domestic-supply story with a limited roster.
Intel’s foundry push has consumed billions and has yet to announce a large external customer for its most advanced nodes, which is why the Piper Sandler note reads as both encouragement and warning. Interest is not commitment. Evaluating a process is cheap and noncommittal: designers study specifications, run test wafers and weigh the risk of moving a product onto an unproven line. A note listing eight companies as evaluators describes curiosity, not demand.
The pool of potential customers is larger than it once was. Companies that built their own fabs for decades increasingly rely on external manufacturing, and a design house that wants a second option has few places to turn. That scarcity is Intel’s strongest argument and, at the same time, its deadline, because a customer that cannot wait will sign elsewhere.
Concentration at TSMC has been a subject of concern for years, in Washington and in boardrooms. Clients have watched export controls, natural disasters and simple demand surges interrupt the flow of the most advanced chips, and each interruption strengthens the case for a backup. Intel is the only American company attempting to offer that backup at the most advanced nodes, which gives its foundry plan a strategic weight beyond its commercial prospects.
Specifications that look good on paper do not ship products. A process has to reach volume yields, and reaching them takes time and customers willing to absorb early risk. The finding that Intel’s metrics beat expectations is encouraging, and it is also the sort of statement made before the hardest part of the work is finished.
The calendar is the binding constraint. A 2028 ramp requires decisions in 2026 and 2027, because equipment lead times and process qualification run into years and cannot be compressed. A customer that signs late misses the window it signed for, which is why the note frames the next several months as the decisive stretch.
Intel’s position is unusual for a company of its size. It designs chips that compete with its prospective customers’ products, and it operates factories that would build those customers’ designs, two roles that pull in opposite directions. Managing that conflict is part of what any anchor customer will be asked to accept, and it is a different kind of negotiation from the usual supply agreement.
The unresolved question is whether interest converts. Eight names evaluating a process is a strong starting position and a weak guarantee, and Intel’s record with external customers makes the difference worth watching rather than assuming. The company has roughly a year to turn a list of interested parties into the single commitment its plan requires.