For most of the summer, investors in Bloom Energy asked the same question on every call and in every hallway conversation: what happens to revenue when Nebius stops being most of the business. On Thursday the company answered it with numbers.
Bloom reported third-quarter revenue of $1.24 billion, up 138% from a year earlier and roughly 15% above what analysts had expected. Product revenue reached $1.07 billion, up 179%. Operating income came in at $230 million against expectations of $170 million, a margin of 18.2%, according to the company’s results published after the close on Thursday.
The company also raised guidance, telling investors on the earnings call that demand had outrun its prior plan. Full-year revenue is now expected at $4.4 billion to $4.6 billion, up from a prior range of $3.9 billion to $4.2 billion. Non-GAAP operating income guidance rose to $960 million to $1.03 billion.
The stock fell anyway. The gap between what Bloom reported and how the shares traded is the argument investors have been having since the summer.
The dispute comes down to what the price already assumes. A company that beats on revenue, beats on margin and raises guidance twice in a year would normally get a higher multiple, not a lower one. Bloom instead trades like a stock whose price already assumes several good years, and each quarter becomes a test of whether the assumptions still hold.
The Nebius question was the most concrete of them. In the second quarter, about 70% of revenue came from a single customer, and the market worried aloud that the pipeline behind it was thin, leaving a gap once that buildout finished. Bloom’s answer is that other data-center customers picked up the work. The Oracle Jupiter project, a contract investors had counted on for a contribution, neither added to nor subtracted from revenue in the period.
Customer concentration remains the structural worry. A business that sells large, multi-megawatt systems to a handful of buyers will always have lumpy quarters, and the disclosure that one client dominated a prior period makes every subsequent quarter harder to forecast from the outside.
Management has argued that the right way to read the order book is by contracted backlog rather than by quarterly concentration, and that customers buying multiple sites show up as separate orders rather than as one visible relationship. Sell-side analysts have largely accepted that framing, with a caveat: backlog is only as good as the deposits behind it.
Cash is the second worry. Bloom reported negative free cash flow of about $180 million for the quarter. Growth in equipment sales consumes working capital, and the company has been building inventory ahead of deliveries. Investors who focus on cash rather than bookings read that line as the real constraint on how fast Bloom can grow without raising money again.
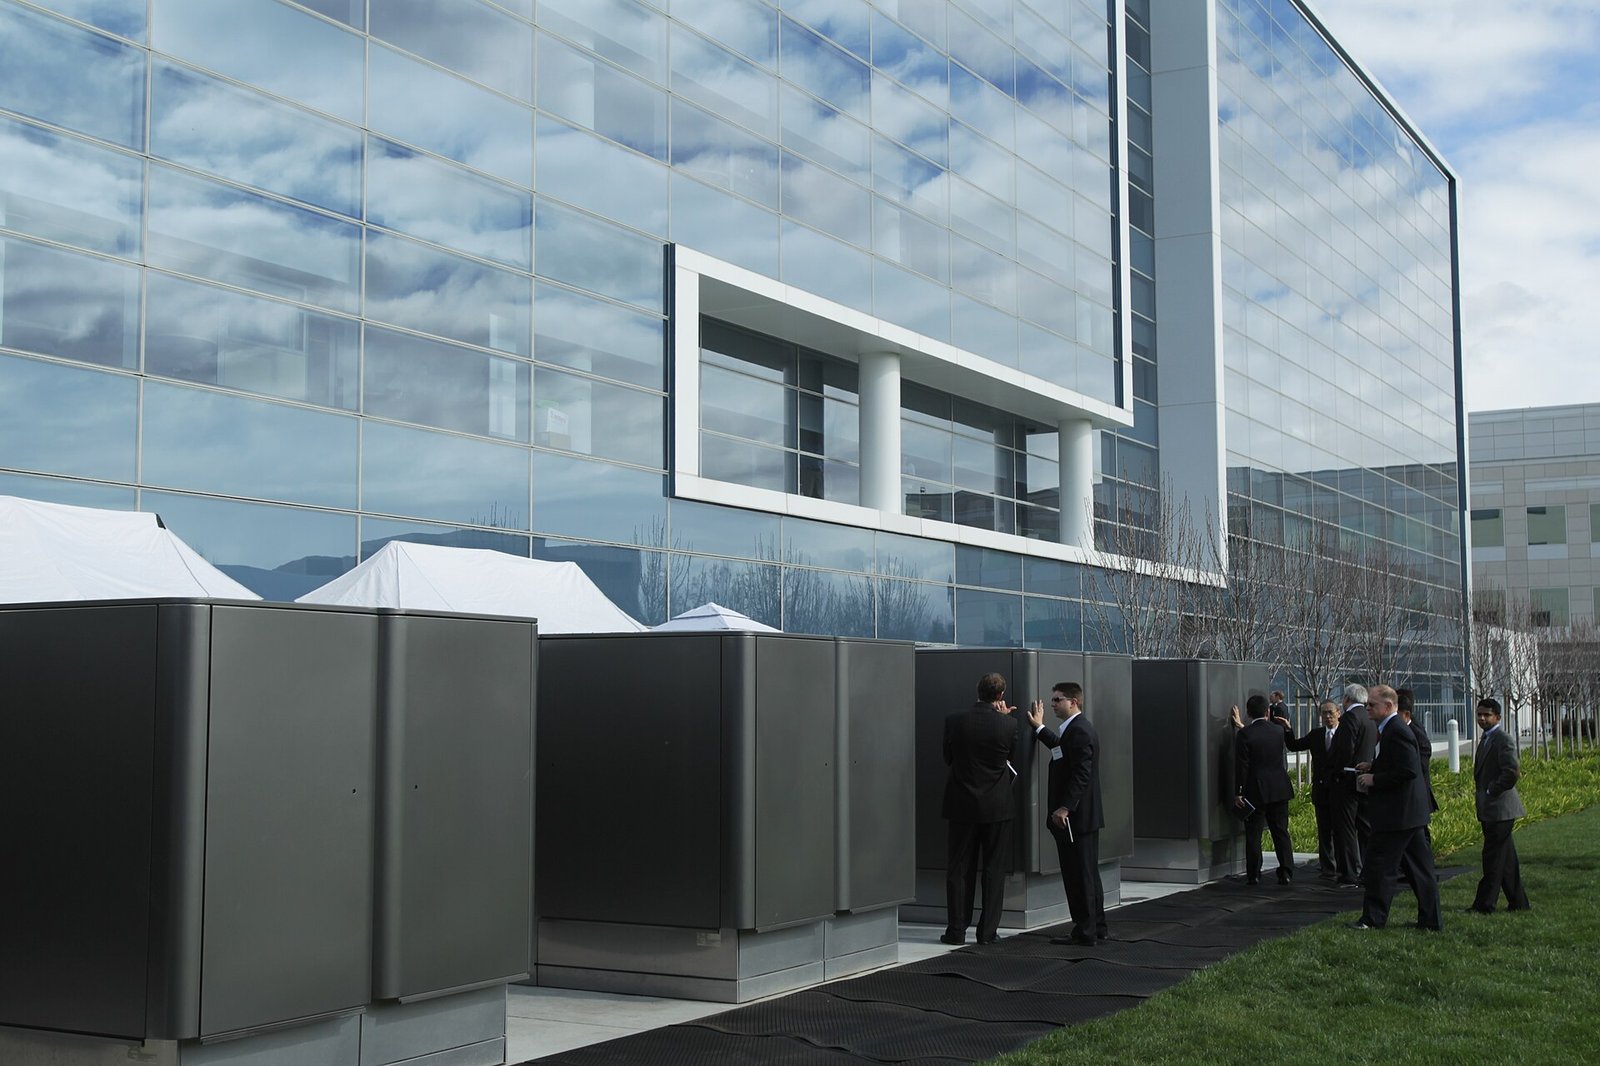
The business itself sits in a narrow but valuable place. Bloom makes solid-oxide fuel cells that generate electricity on-site, converting natural gas into power without a turbine. For data-center developers stuck in interconnection queues that stretch years, a system that can be permitted and switched on behind the meter is worth a premium, even at fuel costs that make utilities nervous.
That is why the order book has grown faster than the manufacturing footprint. Bloom has spent the past two years expanding production capacity, and the guidance increase implies it expects to ship more in the fourth quarter than it did in the third.
Competition has shaped the story too. Bloom’s pitch is speed, and its rivals sell either cheaper power that takes longer to permit or cleaner power that costs more per kilowatt-hour. Utilities, gas turbine makers and battery developers all compete for the same data-center contracts, and each has spent the past year quoting shorter lead times than it did in 2024.
Analysts said the quarter removes the immediate bear case. The concentration risk did not show up as a revenue hole, the margin held, and the guidance raise was large enough to be credible rather than cosmetic. Several of them also noted that the raise came with a rise in the operating-income guide, which is harder to engineer than a revenue beat.
The bear case that survives is about valuation and durability. Fuel cells have disappointed investors before, in earlier cycles, when orders arrived slower than promised and cash ran out before scale did. Bloom’s current position is stronger than in those cycles, but the stock’s reaction shows that the market is not willing to pay for perfection twice.
There is also the question of what happens when the grid catches up. Part of Bloom’s advantage comes from interconnection delays that make on-site generation the only fast option. If utilities shorten those queues, or if gas turbine lead times come down, the premium for speed shrinks.
For now the company is in the rare position of raising guidance while its shares fall, a combination that usually resolves in one of two ways: either the business keeps beating until the multiple looks reasonable, or the multiple was right and the beats were the peak. The next two quarters decide which.
The company said on the call that the demand is structural, tied to electrification and to the sheer size of the computing buildout. The fourth quarter will test the first half of that claim. The cash flow statement will test the second.