The shares were already down 7% in after-hours trading on Friday. By 9:48 a.m. in Tokyo on Monday they had fallen 13.2% to ¥11,685, the first session in which investors could react to a set of numbers saying the fastest part of the memory cycle had passed.
Kioxia Holdings, the Japanese flash-memory maker, told the market on October 30 that it expects revenue of ¥2.5 trillion and operating profit of ¥2.0 trillion for the three months through December. Both are up less than 1% from the quarter just ended. Analysts had been looking for operating profit nearer ¥2.35 trillion, according to estimates compiled by Bloomberg.
The quarter those figures are measured against was extraordinary. Revenue for July through September reached ¥2.48 trillion, against ¥448.3 billion a year earlier. Operating profit came to ¥1.99 trillion, roughly 80% of sales, a margin almost no chipmaker has sustained. Kioxia also declared its first dividend since listing, ¥90 a share.
What broke the run was price, not volume. The average selling price of its NAND flash rose in the mid-20% range in the September quarter, after a rise of about 70% in the three months before. Shipments grew by a low double-digit percentage. Customers were still buying; they were no longer paying much more for the same bits.
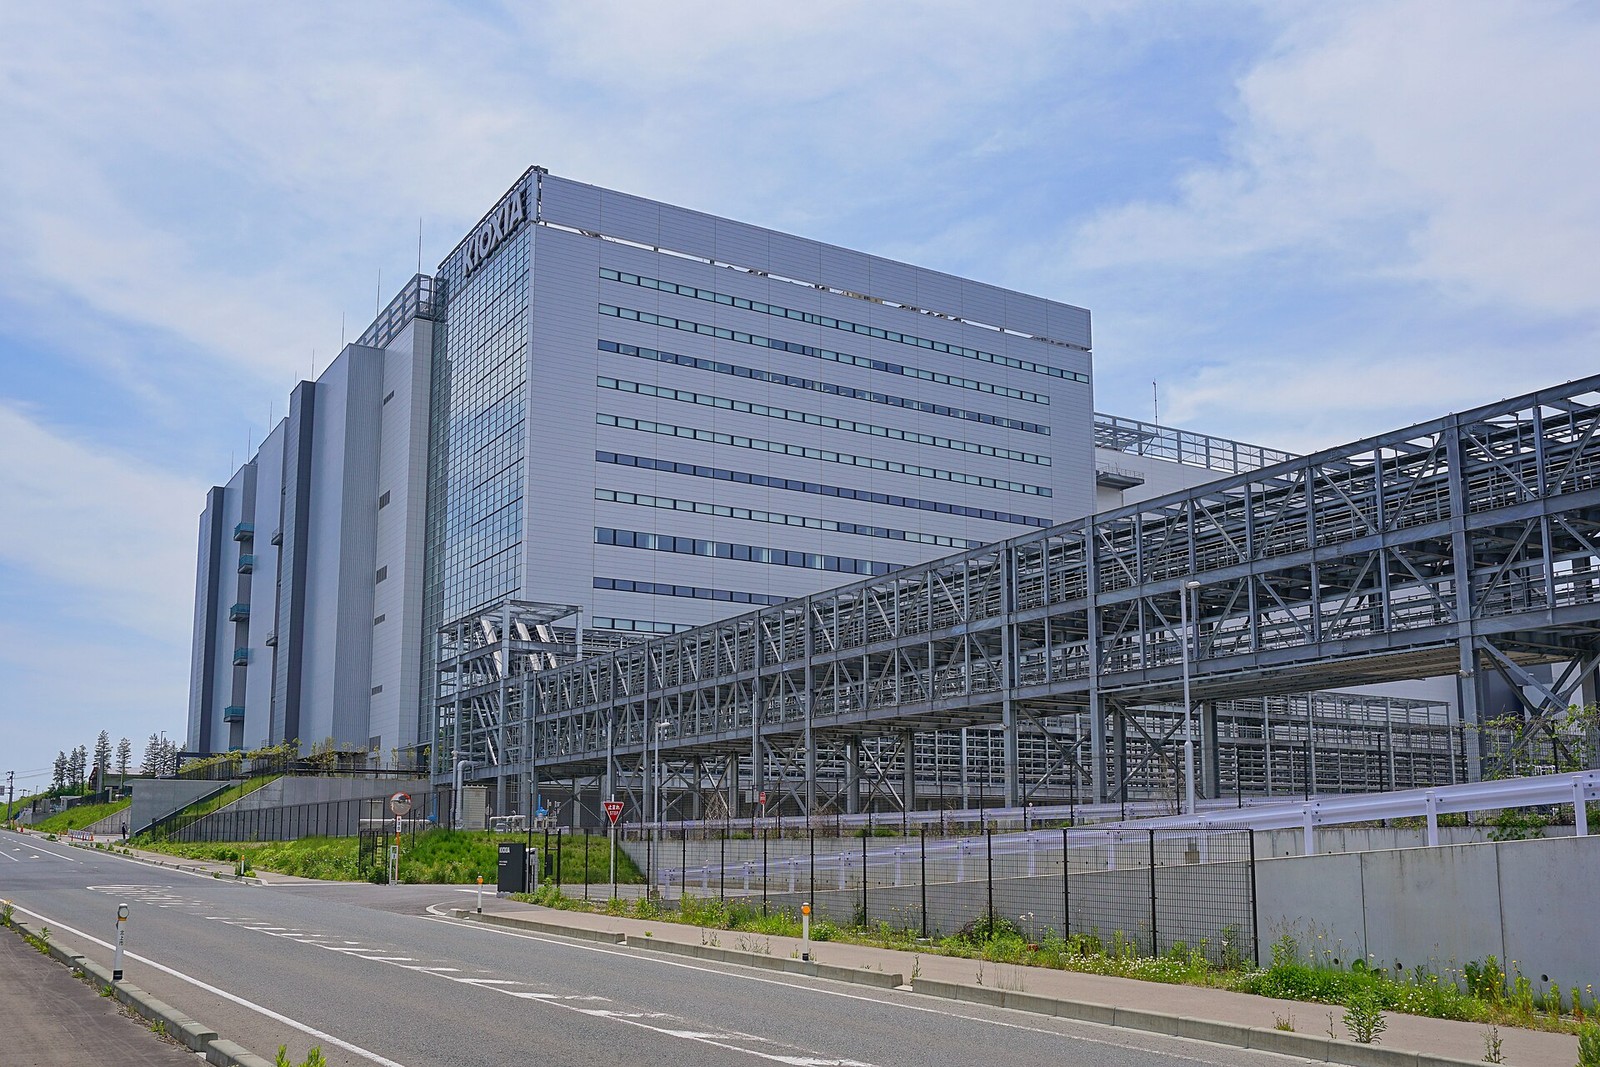
For a company that sells a commodity, that is the whole argument. NAND is made in enormous factories whose cost is fixed once they are built, so profit swings on price. Kioxia runs its flash plants in Mie and Iwate prefectures in joint ventures with SanDisk, the U.S. company spun out of Western Digital, and the two share output and capital spending. The arrangement spreads the burden of a fab that can cost more than $10 billion, and it means the two companies’ fortunes move together: SanDisk fell more than 11% on Friday after the guidance crossed the wire.
The rally Kioxia rode began with data centers. Training and serving large models requires storing enormous quantities of data close to the processors that read it, and the solid-state drives that do that job use NAND. Kioxia’s first-half revenue came to ¥4.25 trillion, up from ¥791.1 billion a year earlier, with operating profit of ¥3.26 trillion against ¥130.8 billion. The six-month operating margin reached 76.9%, a level usually associated with software, not with a business that builds clean rooms.
That is why the guidance mattered more than the results. Kioxia’s October-to-December forecast implies average selling prices rise only modestly and shipments stay roughly flat. Management attributed part of the caution to the yen: the forecast assumes the currency strengthens to ¥157 against the dollar from ¥161, a move that would cost about ¥55 billion in operating profit. The rest is a judgment about how much more customers will pay.
Chief Financial Officer Akira Menju said it was unclear whether prices would keep rising in the fiscal year beginning in April 2027, given how far they had already climbed, according to the company’s earnings briefing. Kioxia still expects the supply shortage to persist through 2027 and has described unit prices as being on an upward trend. It has not said it will stop raising them.
The market’s own forecast points the other way. TrendForce projected on September 30 that NAND contract prices would rise 15% to 20% in the December quarter, faster than the 10% to 15% it had expected for the September quarter. Kioxia’s internal average includes product mix and is measured in dollars, so the two numbers are not directly comparable. Still, the gap between a research firm forecasting accelerating contract prices and a supplier guiding for a flat quarter is the kind of disagreement that gets settled in the next round of monthly price reports.
Early evidence is mixed. Korean trade data cited by industry trackers put a standard 128-gigabit NAND chip at $30.60 in both September and October, after $28.80 in June. That is a pause rather than a decline. Contract prices for the highest-capacity parts used in AI servers are negotiated separately and do not appear in that series.
The split inside memory is the more important story. Contract prices for DRAM and for high-bandwidth memory, the stacked chips that sit beside AI accelerators, are still rising, according to the same industry data. NAND and DRAM are made by overlapping sets of companies but respond to different bottlenecks. High-bandwidth memory is limited by packaging capacity and by how many wafers manufacturers will divert from conventional DRAM. NAND is limited by the pace at which hyperscalers add storage to clusters they have already ordered.
That distinction now separates the stocks. Micron, which sells both DRAM and NAND, fell 5.3% on Friday, and investors have been slower to re-rate the companies whose revenue depends on flash rather than on the memory that sits beside an accelerator.
For customers, a plateau in NAND prices is welcome after a year in which storage costs became a line item in board presentations. For Kioxia, it raises a harder question about what to do with the cash a 77% margin generates. The first dividend is a start. The next decision is whether to spend on capacity that may meet a market already at its peak, or to hold back and let rivals add the wafers.
Kioxia listed in Tokyo in December 2024, when memory prices were recovering from a brutal downturn and investors doubted another cycle would be kind to a company with one product. Two years later the cycle has been kinder than anyone forecast. The guidance issued on Friday is the first time management has told the market that the kindest part may be behind it.