SK Hynix is rebuilding its American organization around the customers who decide how much memory the AI buildout consumes. The company is expanding its U.S. headquarters staff, and SK Group said it will name additional executives and restructure the U.S. business around December 3. The vehicle for the push already exists: a U.S. AI investment subsidiary with a ceiling of up to $10 billion.
The reorganization is the part that costs nothing and signals the most. A memory maker’s American presence has traditionally been a sales office attached to a fab. SK Hynix is turning it into a management layer with its own executives, which is what a supplier does when the customer relationship has become an engineering relationship.
Nvidia and Microsoft are the two names attached to the move. Both are buying memory in volumes that did not exist three years ago, and both make allocation decisions that a Korean headquarters cannot influence from across the Pacific. Being in the room, in the same time zone, with authority to commit, is the difference between a vendor and a partner.
The $10 billion is the number to hold onto. It is a ceiling on the AI investment subsidiary rather than a check already written, and the distinction matters for anyone trying to model capex. A ceiling is a statement of intent, and intent in this market has a way of becoming commitment within two quarters.
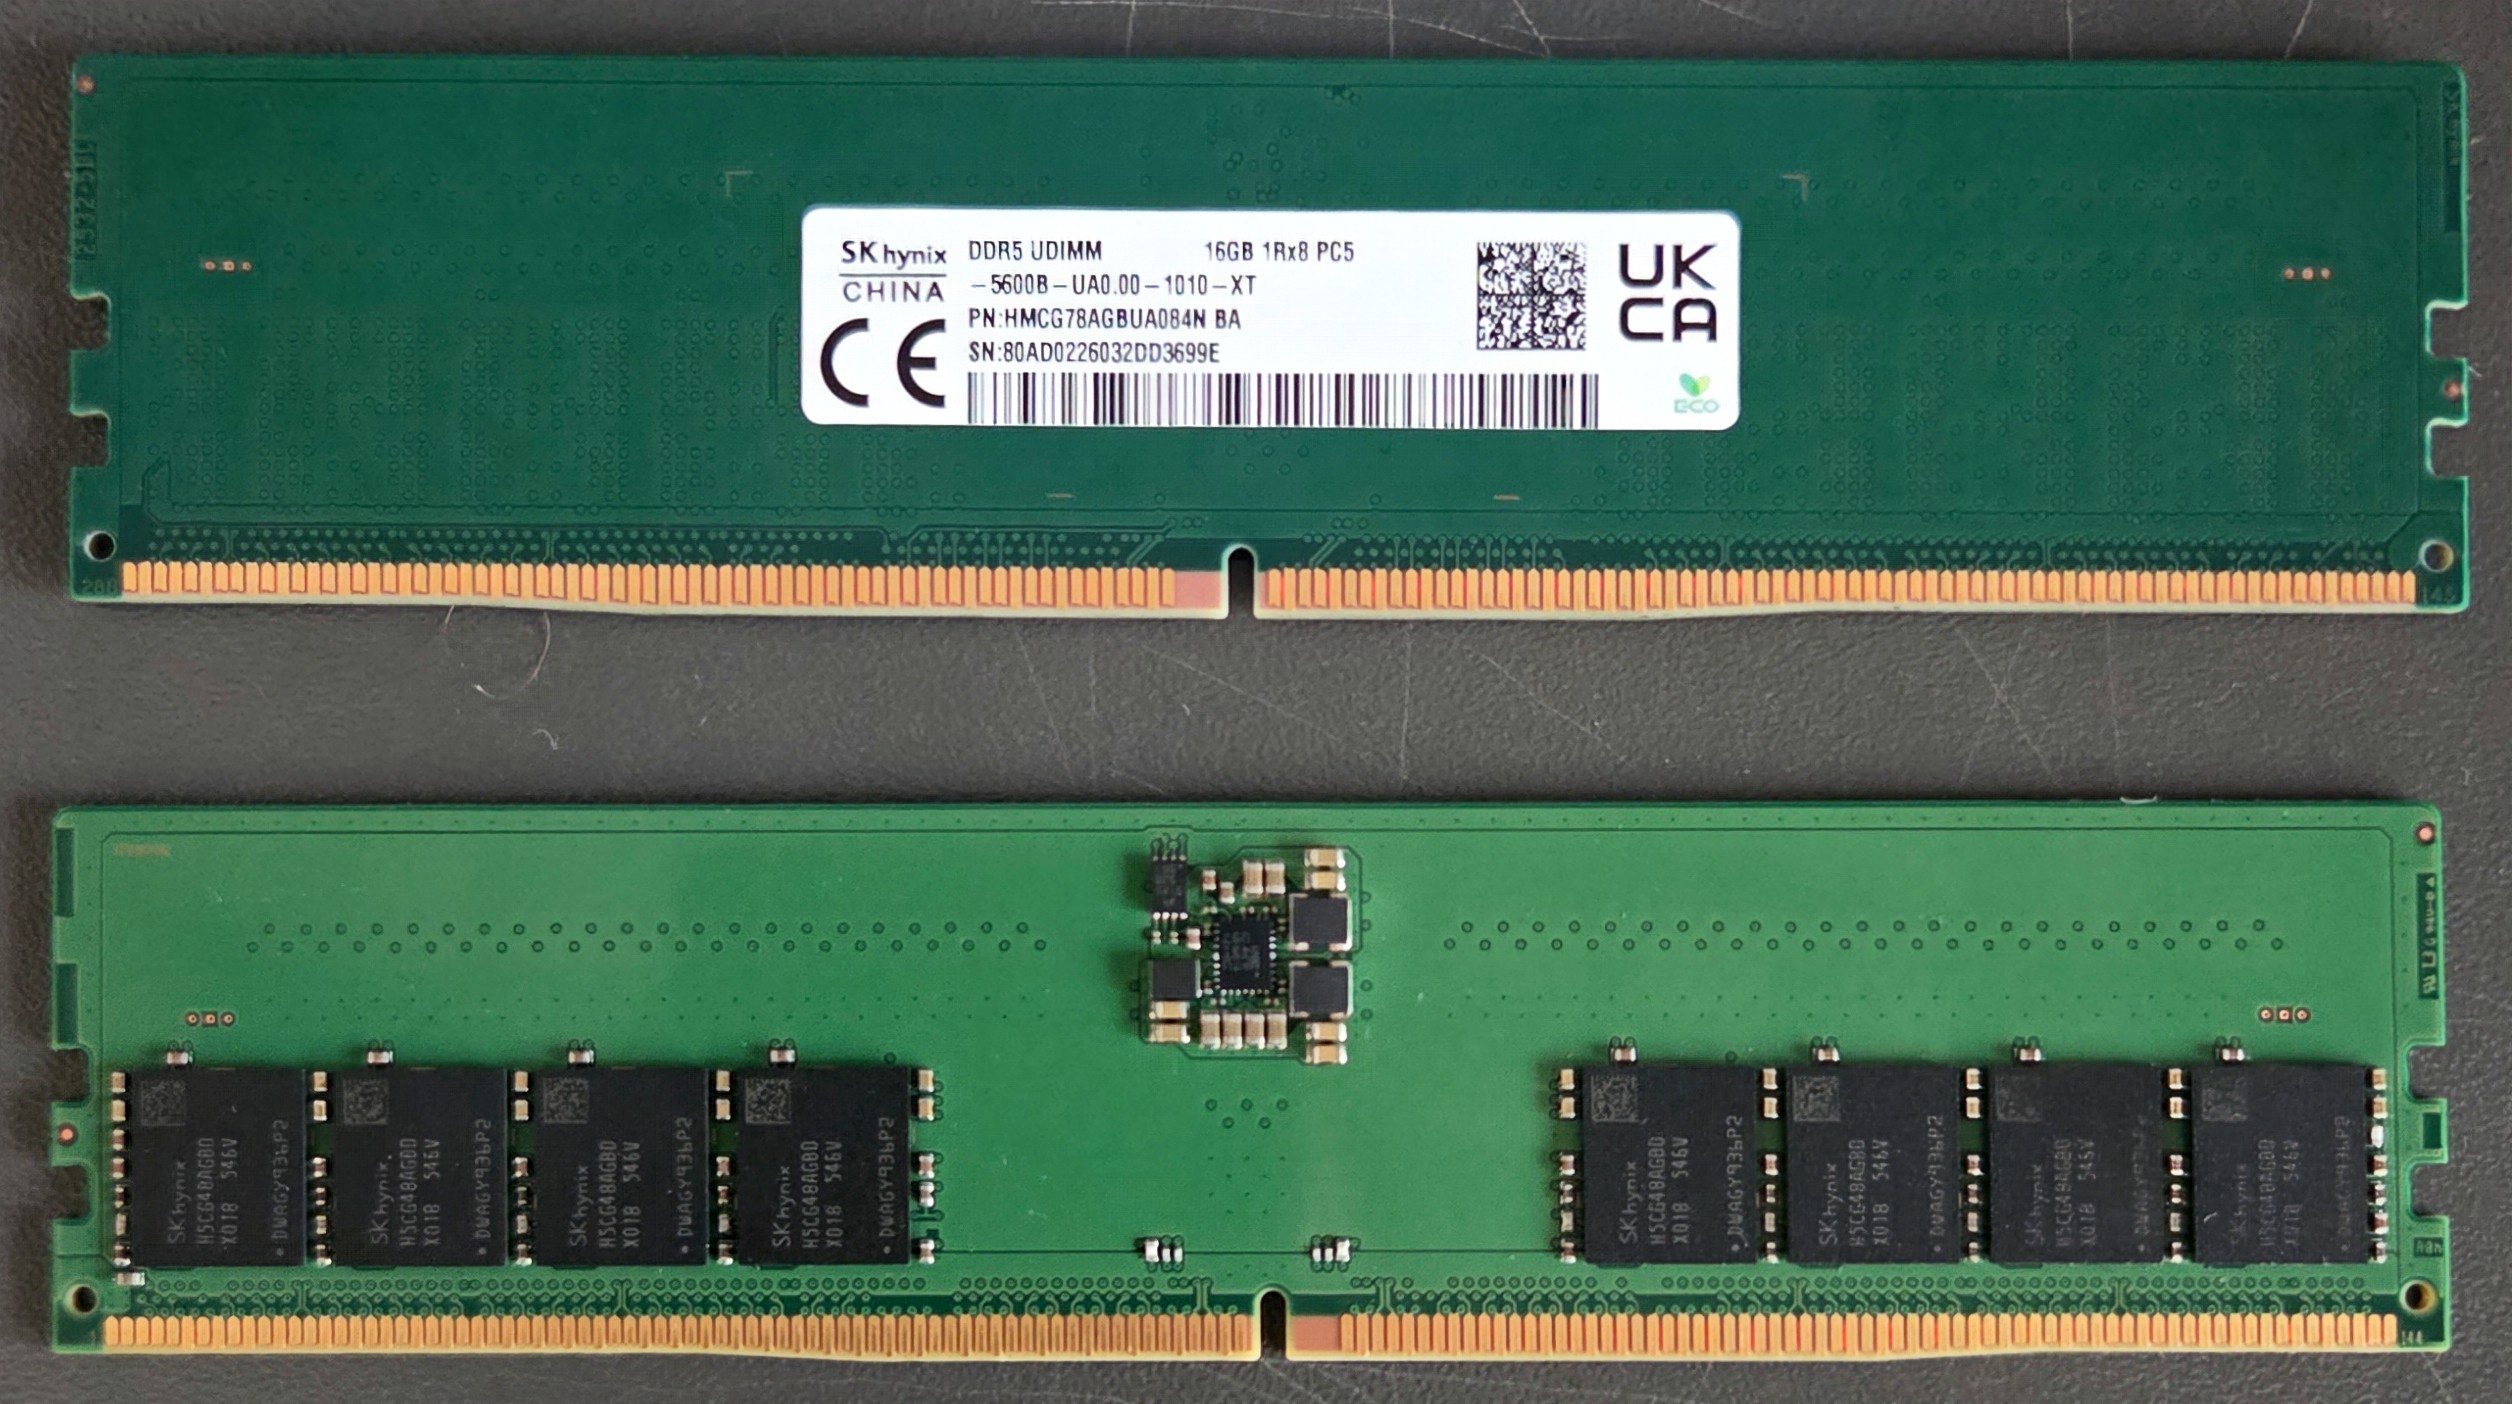
Memory has become the tightest input in the AI supply chain. High-bandwidth memory sits next to the accelerator, and the accelerator is useless without it. That position gives the three surviving suppliers pricing power they have not had since the last shortage, and it gives their customers a reason to want a direct line to the people who allocate wafers.
The December 3 date is a deadline with a purpose. Executive appointments announced before the new year set the shape of the organization for the year that follows, and a restructuring that lands in early December is one that will be staffed, budgeted and operating by the time customers begin their annual negotiations. Announcements in January arrive after the planning cycle has closed.
The American buildout also has a political dimension that a sales office never needed. Memory is now treated as a strategic input in Washington, in the same category as advanced logic. A company with a U.S. subsidiary, U.S. executives and a U.S. investment budget has a different conversation with policymakers than one that ships from Icheon and answers questions by email.
The subsidiary structure gives the company a way to spend without building. Stakes in suppliers, joint development agreements and prepayments to equipment makers can all be routed through an investment arm, and each of them buys influence over capacity without the lead time of a fab. That flexibility is worth more in a shortage than in a boom, because the scarce good is not money but priority.
The risk in the plan is that org charts are cheaper than factories. SK Hynix has not described what the expanded U.S. team will build, and a subsidiary with a $10 billion ceiling can fund partnerships, stakes and joint development without ever pouring concrete. Investors will eventually ask which of those the money is for, and the answer will determine whether this reads as commitment or as positioning.
There is also the question of talent. Semiconductor organizations in the United States are competing for a limited pool of engineers with the same handful of companies, and a Korean firm building an American management layer has to hire people who could work at Nvidia or Microsoft instead. Compensation is part of it. Proximity to the customer’s roadmap is the better argument, and it only works if the U.S. team is actually given decisions to make.
The competitive context is unforgiving. Samsung is buying extreme ultraviolet tools at a scale that will determine its DRAM capacity for the rest of the decade, and Micron is pushing density on the module side. Allocation of the tightest equipment and the tightest customers is a zero-sum exercise, and every supplier is trying to lock in both at once.
For customers, the reorganization is mostly good news with a complication. A supplier with local authority moves faster on qualification and customization. A supplier with a local investment arm also becomes a shareholder in the ecosystem, which creates ties that procurement departments have to think about.
The test of the December announcement will be simple. If SK Hynix names executives with budget authority and customer ownership, the $10 billion ceiling is the beginning of a strategy. If it names coordinators, the ceiling is a press release. The market will know within a quarter, because the customers will start treating the U.S. team as the place where decisions are made.